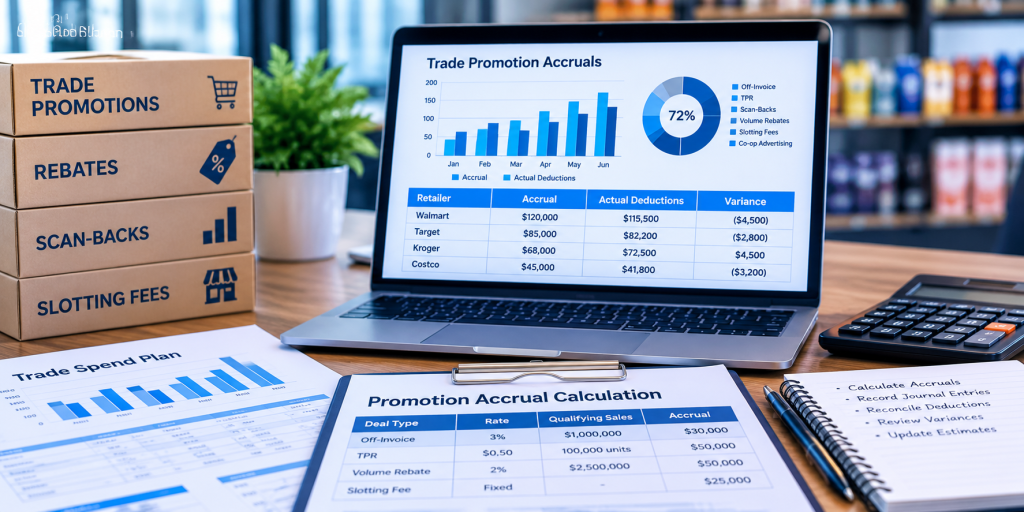
A trade promotion accrual estimates the promotional costs you owe customers for sales already shipped. You record it as a liability and a reduction of revenue in the period of the sale.
Accrual accounting matches trade spend to the sales that earn it, not to the date a retailer deducts it.
As a result, estimate errors reach your P&L, your balance sheet, and your audit file.
This guide serves CPG finance teams. Specifically, it explains how to calculate accruals, book the entries, and fix variances before year end.
In this blog, you’ll learn:
- Accruals estimate promotional costs when you ship, not when the retailer deducts.
- Under ASC 606, most trade promotions reduce revenue as variable consideration.
- The calculation depends on the deal: percentage of sales, per-unit rate, fixed fee, or tiered rebate.
- True-ups and reversals keep the liability honest, so track accrual-to-actual variance monthly.
- Deduction reconciliation closes the loop between retailer claims and your accruals.
- Controls and an audit trail protect your year-end numbers.
What Are Trade Promotion Accruals?
Trade promotion accruals are liabilities you record for promotions that customers will claim later. Retailers usually settle by deducting from invoices, so cash moves weeks or months after the sale.
Therefore, finance must estimate the cost at shipment. Otherwise, margins look better than they are until the deductions arrive.
Accrual vs Trade Spend vs Deduction
| Term | What It Means | When It Happens |
|---|---|---|
| Trade spend | Total funding you give customers to drive sales | Planned and committed over the promotion period |
| Accrual | Your estimated liability for promotions customers earned | Recorded when the related sale ships |
| Deduction | The amount a retailer short-pays against an invoice | Taken when the retailer settles, often weeks later |
Together, these terms describe the trade spend accrual cycle: you commit spend, accrue the cost, and settle through deductions.
What Types of Trade Spend Need Accruals?
Promotional and operational trade spend both create liabilities, but they behave differently.
| Category | Examples | Accrual Approach |
|---|---|---|
| Working trade spend | Off-invoice discounts, TPRs, scan-backs, displays, retailer ads | Accrue as related sales ship or scan |
| Non-working trade spend | Slotting fees, listing fees, fixed allowances | Accrue per contract terms |
| Volume rebates | Tiered and growth incentives | Estimate the full-year rate |
| Operational deductions | Shortage claims, compliance fines, spoilage allowances | Track apart from promotions and classify with your auditors |
Working spend directly influences shoppers at the shelf. In contrast, non-working spend secures access and placement.
Therefore, track the two separately, because they differ in timing and in how you forecast them.
How Does ASC 606 Treat Trade Promotions?
Under ASC 606, payments to customers usually reduce the transaction price, which reduces revenue. However, the exception applies when the customer provides a distinct good or service at fair value.
Promotions you expect to pay are variable consideration. Estimate them using the expected value or the most likely amount.
Accrual accounting also requires you to update the estimate each reporting period. Professional CPG accounting services can help businesses review trade promotion accruals, reconcile deductions, and record accurate true-up adjustments through revenue.
| Payment Type | Typical Treatment | Why |
|---|---|---|
| Off-invoice discounts, TPRs, scan-backs, and rebates | Reduction of revenue | Price concession with no distinct service |
| Slotting fees | Usually a reduction of revenue | Shelf access is generally not a distinct service |
| Co-op advertising for a measurable ad | Can be a marketing expense | Distinct service at fair value |
| Payments above fair value | Excess reduces revenue | Not exchanged for fair value |
Therefore, because contract terms drive the answer, confirm your treatment with your auditors.
How Are Trade Promotion Accruals Calculated?
Multiply the deal rate by the qualifying sales or volume, then adjust for the share you expect the customer to earn.
Accrual = Deal rate × Qualifying volume × Expected earn rate
The right base depends on the deal structure. Specifically, the table shows four common types.
| Deal Type | Accrual Basis | Example |
|---|---|---|
| Percentage off-invoice | Percent of shipped sales | 3% on $1,000,000 of shipments = $30,000 |
| Per-unit scan or TPR | Rate per unit times units | $0.50 on 100,000 units = $50,000 |
| Fixed fee for a listing or display | Contract amount, accrued per its terms | $25,000 fee recorded as the terms require |
| Tiered volume rebate | Expected rebate rate on all qualifying sales | 2% if you expect to reach the 500,000-case tier |
For tiered rebates, estimate the full-year rate and apply it to each sale from the first shipment. Next, update the rate as volume results arrive.
Sell-In vs Sell-Out Accrual Bases
Most teams accrue on sell-in, which means shipments. In contrast, scan-based promotions pay on sell-out, which means retailer sales to shoppers.
Therefore, accurate accruals need both shipment data and consumption data. Without both, you estimate more and true up more.
What Is the Journal Entry for a Trade Promotion Accrual?
Take a 3% off-invoice allowance on $1,000,000 of shipments. Later, the retailer deducts $28,500.
| Step | Debit | Credit | Amount |
|---|---|---|---|
| 1. Record the accrual at shipment | Trade promotion expense (contra-revenue) | Accrued trade promotion liability | $30,000 |
| 2. Retailer deducts $28,500 | Accrued trade promotion liability | Accounts receivable | $28,500 |
| 3. True-up the remaining balance | Accrued trade promotion liability | Trade promotion expense (contra-revenue) | $1,500 |
The accrual was $30,000, and claims totaled $28,500. Therefore, the business over-accrued by $1,500, or 5%.
Many companies show the debit as a deduction from gross sales, so net revenue falls by the accrual. Also, some label the credit a refund liability.
Therefore, follow your chart of accounts and your auditors’ guidance on labels.
What Is an Accrual True-Up in Trade Promotion?
An accrual true-up adjusts the liability to match actual claims once a promotion closes. You book the difference to revenue in the period you identify it.
A large true-up at year end signals under-accruing during the year. As a result, quarterly results looked better than they were.
In contrast, steady small true-ups show your estimates track reality.
What Is an Accrual Reversal in Trade Promotion?
An accrual reversal releases balances that customers will not claim, such as expired or unearned promotions. You credit the amount back to revenue.
Some teams use auto-reversing entries each month and rebook the updated estimate. Meanwhile, others adjust the balance in place.
Also, document why you released the balance and who approved it.
What Is Accrual-to-Actual Variance in Trade Spend?
Accrual-to-actual variance is the gap between what you accrued and what customers actually claimed. Track it by customer, promotion type, and month.
Variance % = (Actual claims − Accrued amount) ÷ Accrued amount
In the earlier example, ($28,500 − $30,000) ÷ $30,000 equals −5%. Therefore, a negative result means over-accrued, and a positive result means under-accrued.
There is no universal accuracy benchmark. Instead, agree a tolerance with your auditors based on materiality.
How Do You Reduce Trade Accrual Variance?
- Use deal terms, not last year’s rate: base each rate on signed agreements and approved promotion plans.
- Accrue on actual shipments or scans: avoid flat monthly estimates.
- Update rates when performance changes: revise rebate rates as volume results arrive.
- Review variance monthly by customer: recurring gaps usually trace to one retailer or one promotion type.
- Close promotions promptly: set a claims window, then true-up or release the balance.
- Share the promotion calendar: finance cannot see timing changes unless sales communicates them.
How Do You Reconcile Deductions to Trade Accruals?
Retailers rarely pay the full invoice. Instead, they short-pay and deduct promotional allowances, fees, and penalties.
- Capture the deduction: pull the remittance and claim detail from the retailer portal or bank.
- Validate it against terms: check the agreement, dates, rates, and proof of performance.
- Match it to an accrual: link the claim to the promotion and customer it relates to.
- Classify it: separate valid trade claims, invalid claims to dispute, and non-trade items such as shortages or compliance fines.
- Clear or dispute it: apply valid trade against the accrual and dispute the rest.
- Review the remaining balance: true-up or release what claims will not use.
Dispute invalid claims instead of absorbing them. Otherwise, you hide the real variance.
How Do Trade Accruals Affect a CPG Company’s P&L?
Trade spend is often one of the largest deductions from gross revenue in CPG. Therefore, accrual errors move net revenue, gross margin, and the balance sheet at once.
| Error | P&L Effect | Balance Sheet Effect |
|---|---|---|
| Under-accrual | Net revenue and margin overstated | Liability understated |
| Over-accrual | Net revenue and margin understated | Liability overstated |
| Trade spend booked as SG&A | Net revenue and gross margin overstated; operating income unchanged | No liability change |
| Late true-up at year end | Quarterly results shift into Q4 | Liability corrected late |
Under-accruing flatters results until the true-up arrives. In contrast, over-accruing builds a cushion that later releases into revenue.
Consequently, both patterns weaken trust in your forecasts.
Above-the-Line vs Below-the-Line Trade Spend
Contra-revenue items sit above the line and reduce gross revenue to arrive at net revenue.
In contrast, SG&A items sit below the line. Therefore, misclassifying above-the-line items as SG&A overstates net revenue and distorts margin reporting.
What Are the Best Practices for Managing Trade Promotion Accruals?
Together, these ten practices keep estimates supportable and variances small.
- Align sales and finance: share the promotion calendar, rates, and changes so accruals reflect what actually runs.
- Treat accruals as estimates: small monthly variances are normal, so watch trends instead of single months.
- Set a materiality threshold: agree with auditors which variances need escalation.
- Base estimates on facts: use signed terms, shipment data, and history, never the result someone wants.
- Protect year-end accuracy: the year-end liability and the P&L must show real obligations, not padded or minimized balances.
- Document every adjustment: record the rationale and get sales approval for changes.
- Involve the controller early: controllers often hold information that changes the estimate.
- Keep an audit trail: store calculations, changes, and support for each promotion.
- Review post-year-end claims: test deductions received after year end against the prior-year accrual.
- Improve continuously: use audit findings and variance trends to refine your method.
How Do You Audit Trade Promotion Accruals?
Auditors test whether your estimate is reasonable and supported. Therefore, prepare your evidence before they ask.
Keep these items ready for each material promotion:
- Signed agreements and approved promotion plans.
- Shipment and scan data behind the calculation.
- The accrual calculation and any manual overrides.
- Claims and deductions received after period end.
- Approval records for every adjustment.
- Proof of performance for key promotions.
Also, a subsequent-claims review is a strong test of your estimate. If claims after year end exceed the accrual, expect questions about your method.
How Do You Close Trade Accruals at Year End?
Year end concentrates every weakness in your process. Therefore, run this checklist before the books close.
- Cut off shipments and promotions: confirm each promotion falls in the right period.
- Refresh estimates: update rates and volumes with the latest results.
- Reconcile open deductions: match unapplied claims to accruals.
- Test subsequent claims: compare early-year deductions with the prior-year accrual.
- Release or true-up: adjust balances that claims will not use, and document why.
How Do You Forecast Trade Accruals?
To forecast trade spend accruals, start with planned promotions by customer and month. Next, apply deal rates to forecast volume and compare the result with history.
Add expected earn rates for rebates and tiers. Finally, compare forecast accruals with actual claims and refine the rates each quarter.
Also track trade rate, which is trade spend divided by gross revenue. For example, a 15% target on $5,000,000 of revenue gives a $750,000 trade budget.
When Do TPM Software and Specialist Support Help?
Spreadsheets struggle once promotions, customers, and deductions multiply. Moreover, a trade promotion management system can connect plans, shipments, and claims, so accruals update as data changes.
If you are ready to move off spreadsheets, explore our trade promotion management software for CPG teams.
Alternatively, our CPA-led trade promotion management services keep accruals accurate and sufficient.
However, the accounting discipline stays the same either way. Estimates must follow deal terms, shipments, and documented judgment.
Frequently Asked Questions About Trade Promotion Accruals
What are trade promotion accruals?
Trade promotion accruals are liabilities you estimate for promotions customers have earned but not yet claimed.
Therefore, you record them when the related sale ships, so revenue and promotional cost land in the same period.
How are trade promotion accruals calculated?
Multiply the deal rate by qualifying sales or volume, then adjust for the share you expect the customer to earn.
For example, a 3% allowance on $1,000,000 of shipments creates a $30,000 accrual.
What is the journal entry for a trade promotion accrual?
Debit trade promotion expense, which reduces revenue, and credit an accrued trade promotion liability.
Next, when the retailer deducts, debit the liability and credit accounts receivable.
What is an accrual true-up in trade promotion?
An accrual true-up adjusts the liability to actual claims after a promotion closes.
Also, you book the difference to revenue in the period you identify it.
What is accrual reversal in trade promotion?
Accrual reversal releases balances that customers will not claim, such as expired promotions.
Therefore, document the reason and the approver, because the release credits revenue.
What is accrual-to-actual variance in trade spend?
It is the gap between the accrued amount and the claims customers actually take.
Specifically, calculate it as actual minus accrued, divided by accrued, and review it monthly.
How do you reduce trade accrual variance?
Base accruals on signed deal terms and actual shipments or scans, and update rates as results change.
In addition, review variance by customer each month and close promotions promptly.
How do you reconcile deductions to trade accruals?
Validate each deductions and chargeback management against the agreement, match it to its promotion, and clear it against the accrual.
Next, dispute invalid claims, and true-up any balance that claims will not use.
How do trade accruals impact a CPG company’s P&L?
Accruals reduce net revenue in the period of the sale, so errors change net revenue and gross margin.
Specifically, under-accruing overstates results until the true-up, and over-accruing understates them.
How do you audit trade promotion accruals?
Test the estimate against signed terms, shipment data, the calculation, and claims received after period end.
Also keep approvals and proof of performance for material promotions.
How does ASC 606 apply to trade promotions?
ASC 606 treats most trade promotions as variable consideration that reduces the transaction price.
However, a payment for a distinct good or service at fair value can be an expense.
Final Thoughts
Accurate trade promotion accruals depend on three habits. Specifically, estimate from deal terms, reconcile deductions monthly, and document every adjustment.
As a result, accrual accounting turns year end into a review instead of a surprise.
At Expertise Accelerated, our CPA-led team helps CPG finance teams keep trade accruals accurate and audit-ready.
Schedule a free consultation with Expertise Accelerated to review your trade promotion accrual process.
