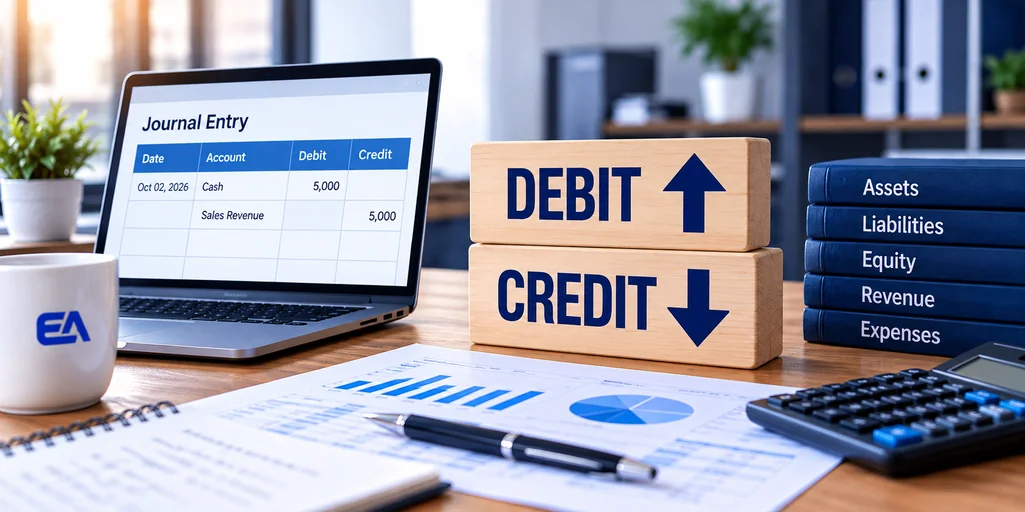
A debit is an accounting entry on the left side of an account. Meanwhile, a credit is an entry on the right side.
Debits increase assets and expenses. In contrast, credits increase liabilities, equity, and revenue.
Bookkeeping starts with debits and credits, yet they confuse almost every new business owner. However, the rules follow one simple pattern.
This guide explains debit vs credit in plain language. Specifically, it covers the rules for all five account types and six worked journal entries.
In addition, it includes a cheat sheet, a trial balance, and the mistakes that throw books out of balance.
Key Takeaways
You will learn the following:
- In debit vs credit, a debit goes on the left side of an account and a credit goes on the right.
- Debits increase assets and expenses, while credits increase liabilities, equity, and revenue.
- Every transaction needs equal debits and credits, so the books always balance.
- Normal balances tell you whether an account is a debit or a credit.
- Debit does not mean bad, and credit does not mean good.
- Your bank statement shows the bank’s point of view, so its debits and credits look reversed.
Debit vs Credit: The Core Difference
The difference between debit and credit is the side of the account. Additionally, each transaction records at least one debit and at least one credit.
The total debits must always equal the total credits. Therefore, the two sides act as a built-in check on your books.
| Feature | Debit | Credit |
|---|---|---|
| Side of the account | Left | Right |
| Abbreviation | Dr | Cr |
| Increases | Assets, expenses, owner’s draws | Liabilities, equity, revenue |
| Decreases | Liabilities, equity, revenue | Assets, expenses, owner’s draws |
| Normal balance | Assets, expenses, owner’s draws | Liabilities, equity, revenue |
| Example | Cash received from a customer | Sale recorded as revenue |
Specifically, the term normal balance means the side that increases the account. For example, cash normally carries a debit balance, so a debit raises it.
Only double entry systems use debits and credits. In contrast, single entry systems record each transaction once.
A Simple Way to Picture Debits and Credits
Think of each entry as a transfer of value. Value moves from the credited account to the debited account.
For example, paying rent moves value out of cash, so cash gets a credit. It moves value into rent expense, so that account gets a debit.
Where the Terms Debit and Credit Come From
The terms first appear in Luca Pacioli’s 1494 mathematics book, which described Venetian bookkeeping. Translators later turned the Latin debere, to owe, and credere, to trust, into debit and credit.
Historians also trace the abbreviations Dr and Cr to those same Latin roots.
When to Debit or Credit: Rules for the Five Account Types
Every account in your chart of accounts falls into one of five types. Consequently, each type follows one rule.
| Account Type | Normal Balance | Debit Does This | Credit Does This | Example Accounts |
|---|---|---|---|---|
| Assets | Debit | Increases | Decreases | Cash, accounts receivable, equipment |
| Liabilities | Credit | Decreases | Increases | Accounts payable, loans, credit card balances |
| Equity | Credit | Decreases | Increases | Owner’s capital, retained earnings |
| Revenue | Credit | Decreases | Increases | Sales, service income |
| Expenses | Debit | Increases | Decreases | Rent, payroll, software |
Similarly, owner’s draws follow the expense pattern. They carry a debit balance because they reduce equity.
Also, some charts add gains and losses as two more groups. Gains behave like revenue, and losses behave like expenses.
Contra Accounts Break the Pattern
A contra account carries the opposite balance from its parent account. For example, accumulated depreciation is an asset account with a credit balance.
Likewise, sales returns reduce revenue, so they carry a debit balance. Contra accounts reduce the parent account without erasing its history.
How to Remember Debits and Credits
The DEALER mnemonic helps most beginners. It sorts the six account groups into debit-normal and credit-normal.
| Letter | Account Group | Normal Balance | Increases With |
|---|---|---|---|
| D | Dividends or owner’s draws | Debit | Debit |
| E | Expenses | Debit | Debit |
| A | Assets | Debit | Debit |
| L | Liabilities | Credit | Credit |
| E | Equity | Credit | Credit |
| R | Revenue | Credit | Credit |
The first three letters, D, E, and A, increase with debits. In contrast, the last three, L, E, and R, increase with credits.
Also remember that debit and credit describe sides, not good or bad. For example, a credit to revenue is good news. In contrast, a credit to a loan balance means you owe more.
The Accounting Equation Behind Debits and Credits
Debits and credits exist to keep one equation in balance. Specifically, that equation says assets equal liabilities plus equity.
Assets = Liabilities + Equity
Debits increase assets because assets sit on the left side of the equation. In contrast, credits increase liabilities and equity because they sit on the right side.
Revenue and expenses connect to the equation through equity. In turn, revenue increases equity, so credits increase revenue.
Expenses, however, reduce equity. Because equity decreases with debits, expenses increase with debits.
As a result, every entry keeps the equation balanced. If you debit one asset, you credit another asset, a liability, or equity by the same amount.
Accountants call this two-sided method double-entry accounting, and every modern accounting system uses it.
Debit and Credit Examples With Journal Entries
Six small business transactions show how debit vs credit rules work in practice. Also, each journal entry lists the debit first and the credit second.
1. Owner Invests $10,000 in the Business
| Account | Debit | Credit |
|---|---|---|
| Cash | $10,000 | |
| Owner’s Capital | $10,000 |
Cash is an asset, so the debit increases it. Likewise, owner’s capital is equity, so the credit increases it.
2. Business Buys $2,000 of Equipment on Credit
| Account | Debit | Credit |
|---|---|---|
| Equipment | $2,000 | |
| Accounts Payable | $2,000 |
The business now owns the equipment and owes the supplier. Therefore, total assets and total liabilities both rise by $2,000.
3. Business Invoices a Customer $3,500 for Services
| Account | Debit | Credit |
|---|---|---|
| Accounts Receivable | $3,500 | |
| Service Revenue | $3,500 |
This entry follows accrual accounting, which records revenue when earned. Accounts receivable also shows the amount the customer still owes.
4. Customer Pays the $3,500 Invoice
| Account | Debit | Credit |
|---|---|---|
| Cash | $3,500 | |
| Accounts Receivable | $3,500 |
Cash rises and receivables fall. However, revenue does not change, because the business already recorded it in the third example.
5. Business Pays $1,200 in Rent
| Account | Debit | Credit |
|---|---|---|
| Rent Expense | $1,200 | |
| Cash | $1,200 |
Expenses carry a debit balance, so the debit increases rent expense. Meanwhile, the credit lowers cash.
6. Business Pays the $2,000 Equipment Bill
| Account | Debit | Credit |
|---|---|---|
| Accounts Payable | $2,000 | |
| Cash | $2,000 |
The debit removes the liability, and the credit lowers cash. As a result, accounts payable returns to zero.
Entries With More Than Two Accounts
Some transactions touch three or more accounts. For example, a business records $5,000 in gross wages, pays $3,900 in cash, and owes $1,100 in withheld taxes.
| Account | Debit | Credit |
|---|---|---|
| Payroll Expense | $5,000 | |
| Cash | $3,900 | |
| Payroll Liabilities | $1,100 |
One debit matches two credits, so the entry still balances. This simplified entry leaves out employer payroll taxes.
Also, it sits outside the running example, so it does not change the trial balance below.
Debit and Credit Entries for Common Business Transactions
Most debit vs credit patterns repeat across transactions. Therefore, use this table as a reference when you code entries.
| Transaction | Debit | Credit |
|---|---|---|
| Make a sale for cash | Cash | Sales Revenue |
| Make a sale on account | Accounts Receivable | Sales Revenue |
| Collect a customer payment | Cash | Accounts Receivable |
| Buy inventory with cash | Inventory | Cash |
| Buy inventory on account | Inventory | Accounts Payable |
| Pay a vendor bill | Accounts Payable | Cash |
| Record payroll | Payroll Expense | Cash and Payroll Liabilities |
| Take out a loan | Cash | Loan Payable |
| Pay loan principal | Loan Payable | Cash |
| Owner takes a draw | Owner’s Draws | Cash |
| Record depreciation | Depreciation Expense | Accumulated Depreciation |
| Collect sales tax on a sale | Cash | Sales Tax Payable |
For the last row, the sale itself also credits sales revenue. Specifically, the customer pays the price plus the tax, and the business owes the tax to the state.
Debits and Credits Cheat Sheet: Is It a Debit or a Credit?
Use this debit vs credit accounting cheat sheet to check any account by name. The normal balance is the side that increases the account.
| Account | Account Type | Increases With | Normal Balance |
|---|---|---|---|
| Cash | Asset | Debit | Debit |
| Accounts Receivable | Asset | Debit | Debit |
| Inventory | Asset | Debit | Debit |
| Prepaid Expenses | Asset | Debit | Debit |
| Equipment | Asset | Debit | Debit |
| Accumulated Depreciation | Contra asset | Credit | Credit |
| Accounts Payable | Liability | Credit | Credit |
| Credit Card Payable | Liability | Credit | Credit |
| Loans Payable | Liability | Credit | Credit |
| Unearned Revenue | Liability | Credit | Credit |
| Sales Tax Payable | Liability | Credit | Credit |
| Owner’s Capital | Equity | Credit | Credit |
| Common Stock | Equity | Credit | Credit |
| Retained Earnings | Equity | Credit | Credit |
| Owner’s Draws | Contra equity | Debit | Debit |
| Sales Revenue | Revenue | Credit | Credit |
| Service Revenue | Revenue | Credit | Credit |
| Interest Income | Revenue | Credit | Credit |
| Sales Returns and Allowances | Contra revenue | Debit | Debit |
| Cost of Goods Sold | Expense | Debit | Debit |
| Rent Expense | Expense | Debit | Debit |
| Payroll Expense | Expense | Debit | Debit |
| Depreciation Expense | Expense | Debit | Debit |
| Interest Expense | Expense | Debit | Debit |
| Gain on Sale of Assets | Gain | Credit | Credit |
| Loss on Sale of Assets | Loss | Debit | Debit |
However, retained earnings can carry a debit balance after accumulated losses. Otherwise, each account follows the pattern shown.
T-Accounts: See Debits and Credits Side by Side
A T-account makes debit vs credit easy to see. It draws one account as the letter T, with debits on the left and credits on the right.
The T-account below shows the cash account after the six examples above.
| Cash: Debit (Left) | Cash: Credit (Right) |
|---|---|
| $10,000 Owner investment | $1,200 Rent payment |
| $3,500 Customer payment | $2,000 Equipment bill payment |
| Total debits: $13,500 | Total credits: $3,200 |
| Ending balance: $10,300 debit |
Debits total $13,500 and credits total $3,200. As a result, cash carries a $10,300 debit balance.
How Does a Trial Balance Prove Debits Equal Credits?
A trial balance lists every account balance and totals the debit and credit columns. In addition, the two totals must match.
Here is the trial balance after all six examples.
| Account | Debit | Credit |
|---|---|---|
| Cash | $10,300 | |
| Equipment | $2,000 | |
| Rent Expense | $1,200 | |
| Owner’s Capital | $10,000 | |
| Service Revenue | $3,500 | |
| Totals | $13,500 | $13,500 |
Accounts receivable and accounts payable both have zero balances, so they do not appear. As a result, both columns total $13,500, so the books balance.
However, a balanced trial balance does not catch every mistake. For example, an entry posted to the wrong account still balances.
How Debits and Credits Flow Into Financial Statements
Debit vs credit balances in the trial balance feed the financial statements. Revenue carries credits and expenses carry debits, so net income is the gap between them.
Meanwhile, asset, liability, and equity balances build the balance sheet. Activity in the cash account builds the cash flow statement.
The table below turns the six examples into two of the three statements.
| Statement | Line | Amount |
|---|---|---|
| Income statement | Service revenue | $3,500 |
| Income statement | Rent expense | -$1,200 |
| Income statement | Net income | $2,300 |
| Balance sheet | Total assets (cash $10,300 plus equipment $2,000) | $12,300 |
| Balance sheet | Total liabilities | $0 |
| Balance sheet | Owner’s equity ($10,000 capital plus $2,300 net income) | $12,300 |
Assets of $12,300 equal liabilities of $0 plus equity of $12,300. Therefore, the accounting equation balances.
Lenders review these statements, so entry errors can reach loan applications. As a result, accurate debits and credits protect more than the books.
Debit vs Credit on a Bank Statement
Debit vs credit confuses many owners on bank statements, because statements show the bank’s books, not yours. As a result, the point of view flips.
Your deposit is a liability for the bank, because the bank owes you that money. Credits increase liabilities, so the bank credits your account when you deposit.
Similarly, a withdrawal reduces what the bank owes you. Therefore, the bank debits your account.
| Event | Bank’s Books | Your Books |
|---|---|---|
| Deposit | Credit to your account | Debit to Cash |
| Withdrawal or payment | Debit to your account | Credit to Cash |
Debit cards and credit cards also use these words differently. A debit card spends your own cash, so the entry credits cash.
In contrast, a credit card borrows money. When you buy supplies with a credit card, you debit the expense and credit the credit card liability.
What Are Common Debit and Credit Mistakes?
These debit vs credit errors cause most out-of-balance books. Fortunately, each one has a simple fix.
- Treating debit as bad and credit as good: debit and credit only name the side. The account type decides the effect.
- Copying the bank’s point of view: record deposits as debits to cash, even though the statement shows a credit.
- Posting only one side: every entry needs a matching debit and credit. Accounting software blocks unbalanced entries, but spreadsheets do not.
- Reversing the sides: posting an expense as a credit understates costs and overstates profit.
- Expensing a long-lasting asset: recording a $2,000 laptop as an expense instead of equipment understates both assets and profit.
- Mixing personal and business transactions: personal spending in the business books hides true profitability and complicates taxes.
- Miscoding transactions: an entry in the wrong account still balances. Therefore, review account coding every month.
- Skipping bank reconciliation: reconciling monthly catches missing or duplicate entries before they spread.
How Accounting Software Records Debits and Credits
QuickBooks, Xero, and similar tools use double-entry accounting behind the scenes. As a result, you rarely type a debit or credit by hand.
For example, creating an invoice debits accounts receivable and credits revenue automatically. Recording the payment then debits cash and credits receivables.
However, the software only records what you tell it. A wrong category creates a wrong entry that still balances.
Therefore, someone who understands debits and credits should review the books each month.
When Should You Bring in a CPA for Your Books?
Debit vs credit entries are manageable for a very small business. However, complexity grows quickly with payroll, inventory, loans, and multiple bank accounts.
Therefore, consider professional help when books stay out of balance, reconciliations run late, or lenders ask for financial statements.
Expertise Accelerated provides CPA-led bookkeeping and accounting services that keep your debits, credits, and financial statements accurate.
Frequently Asked Questions About Debit vs Credit
What is the difference between debit and credit in accounting?
A debit is an entry on the left side of an account. Meanwhile, a credit is an entry on the right side.
Debits increase assets and expenses, while credits increase liabilities, equity, and revenue.
Is accounts payable a debit or credit?
Accounts payable is a liability, so it normally carries a credit balance.
A credit increases it when you receive a bill. In contrast, a debit decreases it when you pay.
Is accounts receivable a debit or credit?
Accounts receivable is an asset, so it normally carries a debit balance.
You debit it when you invoice a customer. Then you credit it when the customer pays.
Is revenue a debit or credit?
Revenue is a credit. Credits increase revenue accounts, such as sales and service income.
However, a debit reduces revenue, which happens with refunds and sales returns.
Are expenses debit or credit?
Expenses are debits. A debit increases an expense account, and a credit decreases it.
For example, paying rent debits rent expense and credits cash.
Is retained earnings a debit or credit?
Retained earnings normally carries a credit balance because it is an equity account.
However, a business with accumulated losses can show a debit balance.
Is accumulated depreciation a debit or credit?
Accumulated depreciation is a credit. It is a contra asset account that reduces an asset’s value.
Therefore, each depreciation entry debits depreciation expense and credits accumulated depreciation.
Is a debit good or bad?
A debit is neither good nor bad. It only names the left side of an entry.
For example, a debit to cash is good news because cash rises. In contrast, a debit to rent expense records a cost.
Why does my bank credit my account when I deposit money?
The bank statement shows the bank’s books, where your balance is a liability the bank owes you. Credits increase liabilities, so a deposit appears as a credit.
In your own books, the same deposit is a debit to cash.
Can you debit and credit the same account in one entry?
Not in the same entry. Each entry needs different accounts on its debit and credit sides.
However, an account receives both debits and credits across different transactions.
What happens if debits and credits do not equal?
The books are out of balance, which means an entry has an error or only one side.
Run a trial balance to confirm the gap, then trace the difference to the entry that caused it. Also, a difference divisible by nine often signals transposed digits.
Do I need to know debits and credits if I use QuickBooks?
Yes, at a basic level. The software posts entries automatically, but it cannot tell whether you chose the right account.
Additionally, understanding debits and credits helps you spot miscoded transactions and read your reports with confidence.
Final Thoughts
Debit vs credit becomes simple once you remember three facts. Debits go left, credits go right, and every entry balances.
Next, start with the accounting equation and learn the five account types. Then practice with real transactions until the rules feel automatic.
At Expertise Accelerated, our CPA-led team keeps your books balanced and your financial statements accurate every month.
Schedule a free consultation with Expertise Accelerated to review your books and fix errors before they grow.
